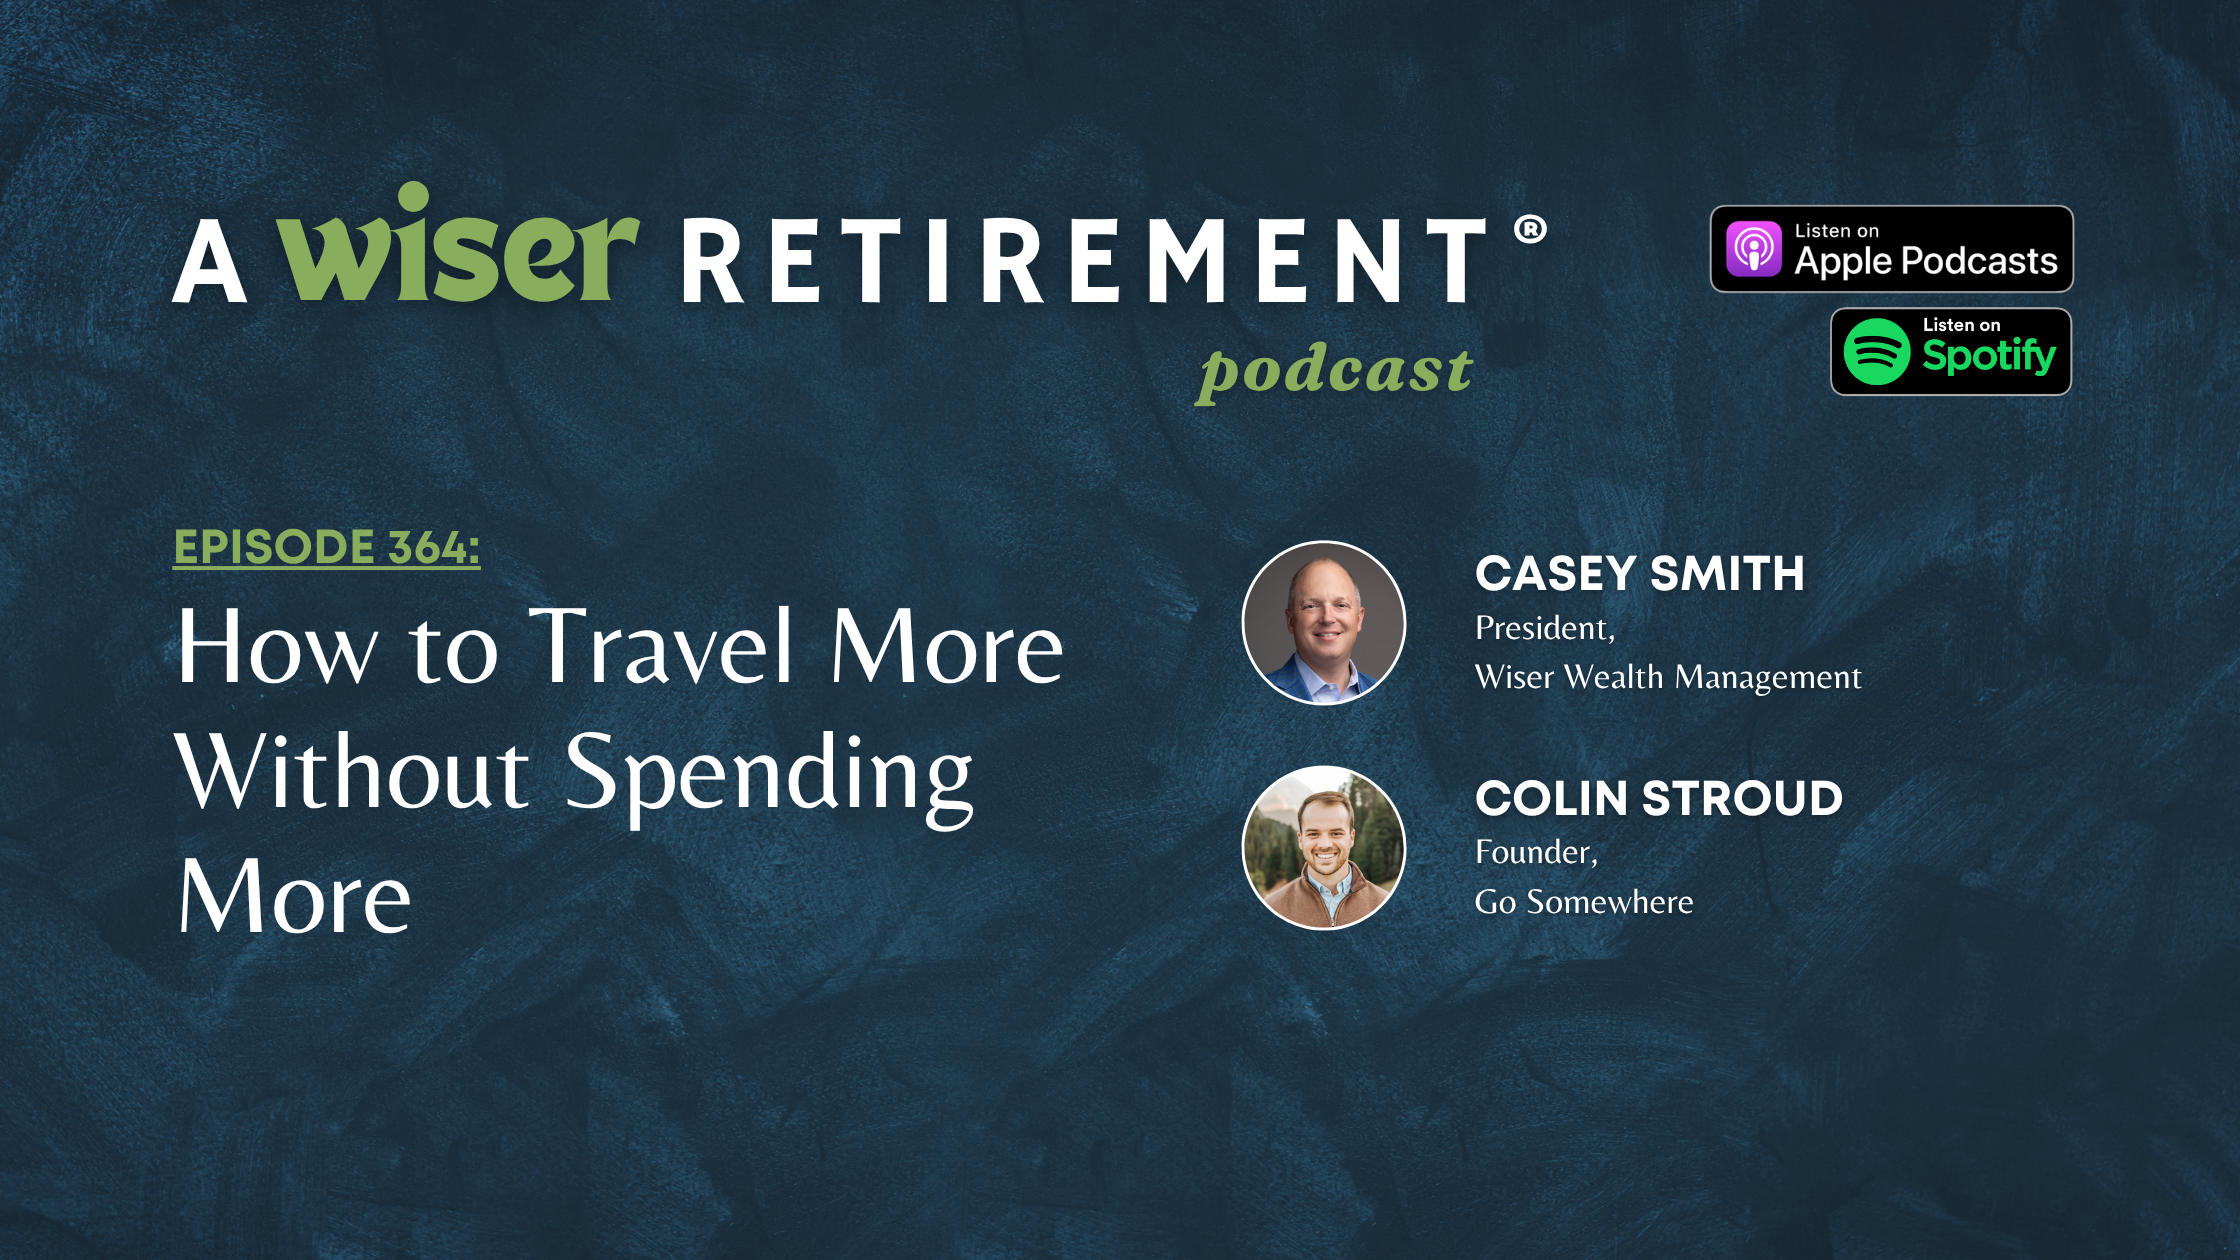
How to Travel More Without Spending More
Your credit card earns points every month, but are they getting you anywhere? A growing rewards balance can feel valuable until you try to turn it into a trip you actually want to take. The opportunity lies in matching your everyday spending with the right rewards, then knowing when a redemption is worth the points, fees, and effort.
In this episode of A Wiser Retirement® Podcast, we discuss how to travel more without spending more. Host Casey Smith welcomes Colin Stroud, Founder of Go Somewhere, to explore credit card rewards, the tradeoffs between points and cash back, and why a simpler strategy sometimes makes more sense.
Listen or Watch
Summary
Credit Card Debt Comes Before Travel Rewards
The conversation starts with a clear boundary: Rewards strategies are for people who can use credit cards responsibly and pay their balances in full. Carrying expensive credit card debt changes the calculation.
Spending more just to earn a welcome bonus also misses the point. Colin distinguishes between prepaying an existing expense, such as car insurance when cash is available, and buying a television primarily to meet a spending requirement. Rewards should work around purchases you already need.
A Premium Card May Not Match Your Spending
Casey brings a personal dilemma to the discussion. He uses an American Express Business Platinum card, but a conversation with American Express raises the possibility that a Gold card could earn more points on his spending.
That surprises him: Shouldn’t the more prestigious card offer the better rewards?
The distinction is between earning points and paying for benefits. A premium card may include lounge access or other services, but those features only matter if you use them. Casey questions the value of lounge access in destinations he does not visit.
Before comparing annual fees, look at where your spending goes and which benefits fit your life. A card’s image does not answer either question.
Cash Back Deserves a Place in the Conversation
Although Colin builds his business around travel rewards, he frequently recommends cash back. Travel points require more decisions, more research, and a willingness to navigate unfamiliar programs.
Consider the family that drives to the Jersey Shore for its annual vacation and has little interest in flying. A complicated airline strategy may offer less practical value than cash back that helps cover the beach rental.
The same applies to someone who already feels overwhelmed. A potentially valuable redemption still requires time and attention. Colin treats personal preference as part of the decision, even when the math points toward a more elaborate approach.
Flexible Points Help, but Family Needs Still Matter
Colin generally favors flexible rewards over committing all spending to one airline or hotel program. Transferable points create options across participating travel partners.
That flexibility does not solve every travel problem. Casey has a family of five, and standard hotel rooms available through points may not accommodate everyone comfortably. A redemption can look appealing until the family needs another room.
For airline pilots with access to standby travel, the priorities may shift toward hotels. Even then, Colin does not automatically recommend a hotel-branded card. Flexible rewards or cash back may fit better, depending on family size, lodging preferences, and how the pilot travels.
Compare the Cash Price With the Points Required
Accumulating rewards is only half the process. The other half is deciding how to use them.
Colin describes a Hyatt stay in St. Kitts with a cash price of approximately $1,500 per night and a redemption requirement of 30,000 points. That difference illustrates the opportunity he looks for: situations where the points price compares favorably with the cash price.
Finding those opportunities may mean reversing the usual planning process. Instead of selecting one hotel and then checking your points, start with available rewards and explore where they might take you.
Casey shares his own example from attending the Masters. He describes finding same-day hotel availability through points while cash prices run much higher. His ability to drive home provides a fallback; the approach depends on circumstances that do not apply to every traveler.
A Luxury Experience and Cash Savings Are Different
One of the episode’s most useful distinctions emerges around a hotel benefit with an annual card fee.
If a card helps you access a stay with a high advertised price, you may receive an experience you otherwise would not purchase. But subtracting the card fee from that advertised price does not necessarily describe money you actually save.
Would you pay that cash rate? Would you take the trip without the benefit? Do you want that particular hotel?
Those questions matter for retirees seeking an occasional getaway and business owners whose expenses generate substantial rewards. A more expensive experience can be enjoyable without representing an equivalent reduction in planned spending.
Give Your Points a Purpose
Colin cautions against accumulating points indefinitely. Redemption requirements can increase, leaving a balance short of the trip someone expects to book. His phrase is straightforward: “Earn them and burn them.”
For people with lower spending, he suggests choosing one manageable strategy rather than opening numerous cards to chase bonuses. Flexibility with destinations can also create options: A place that offers a similar experience may better fit the available budget or rewards.
The next step starts with your existing spending, your travel preferences, and how much complexity you want to manage. For more about Colin’s rewards consulting and points-based travel planning, visit Go Somewhere.
For more questions about your complete financial plan, please reach out to schedule a complimentary consultation with one of Wiser’s financial advisors today!
- Schedule a Complimentary Consultation: Discover how our services can help you achieve financial confidence.
- Access Our Free Guides: Gain valuable insights on topics such as why most financial plans fail, how to leave a financial legacy, post-divorce financial planning, and more!
- Subscribe to A Wiser Retirement® YouTube Channel.
- Listen to A Wiser Retirement® Podcast and access previous episodes.
Connect:
Recent posts
Share This Story, Choose Your Platform!
Wiser Wealth Management, Inc (“Wiser Wealth”) is a registered investment adviser with the U.S. Securities and Exchange Commission (SEC). As a registered investment adviser, Wiser Wealth and its employees are subject to various rules, filings, and requirements. You can visit the SEC’s website here to obtain further information on our firm or investment adviser’s registration.
Wiser Wealth’s website provides general information regarding our business along with access to additional investment related information, various financial calculators, and external / third party links. Material presented on this website is believed to be from reliable sources and is meant for informational purposes only. Wiser Wealth does not endorse or accept responsibility for the content of any third-party website and is not affiliated with any third-party website or social media page. Wiser Wealth does not expressly or implicitly adopt or endorse any of the expressions, opinions or content posted by third party websites or on social media pages. While Wiser Wealth uses reasonable efforts to obtain information from sources it believes to be reliable, we make no representation that the information or opinions contained in our publications are accurate, reliable, or complete.
To the extent that you utilize any financial calculators or links in our website, you acknowledge and understand that the information provided to you should not be construed as personal investment advice from Wiser Wealth or any of its investment professionals. Advice provided by Wiser Wealth is given only within the context of our contractual agreement with the client. Wiser Wealth does not offer legal, accounting or tax advice. Consult your own attorney, accountant, and other professionals for these services.